🎧 Listen to the summary
Table of Contents
- Introduction: Understanding Gold as an Investment
- Section 1: The Fundamentals of Gold IRAs
- Section 2: Purchasing Physical Gold: What You Need to Know
- Section 3: Tax Implications of Gold Investments
- Section 4: Storage Solutions: Protecting Your Gold Assets
- Conclusion: Making the Right Choice for Your Retirement Portfolio
- Frequently Asked Questions
Introduction: Understanding Gold as an Investment
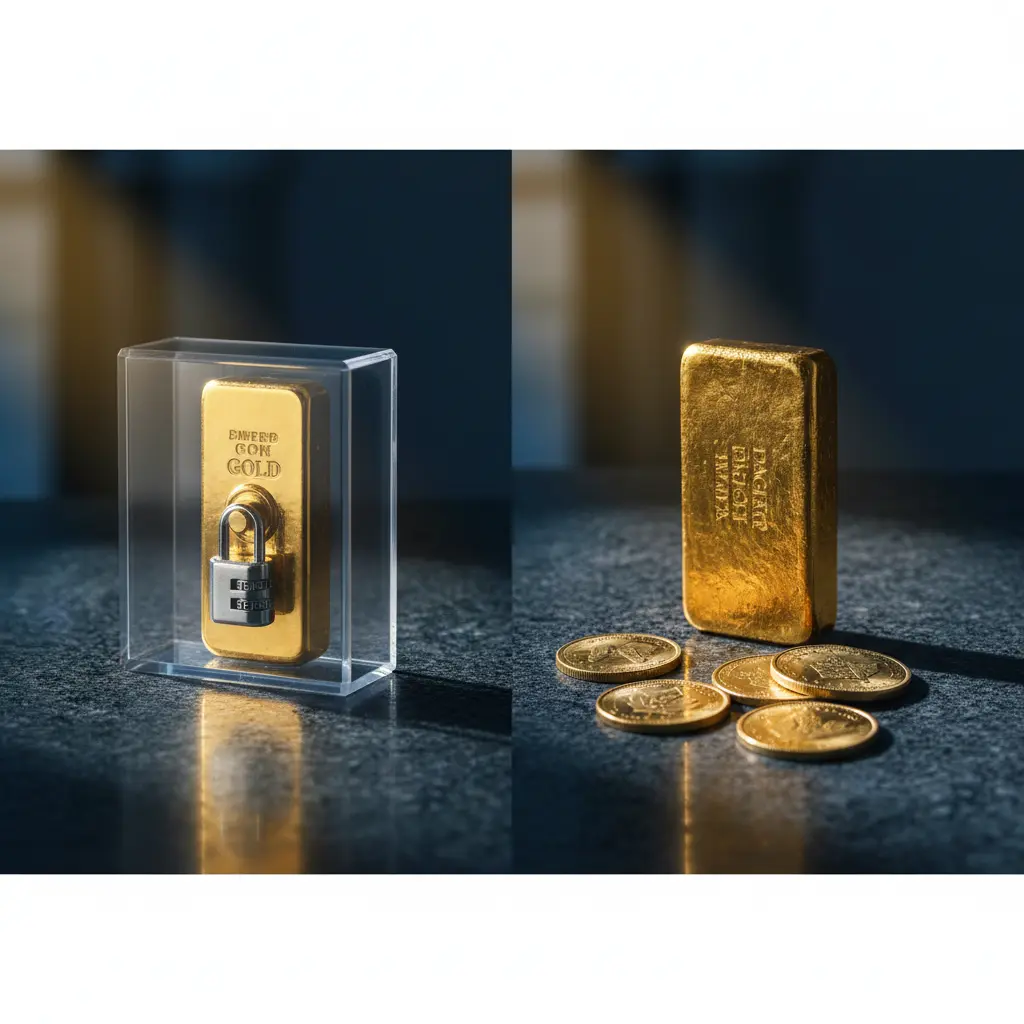
Physical gold provides an uncorrelated hedge against currency debasement and systemic market volatility. When evaluating gold ira vs physical gold, investors must weigh direct possession against custodial tax advantages, alongside liquidity and IRS compliance mandates. Educational resources from the Opulent Gold team outline these structural distinctions.
Two Ways to Own Gold
A self-directed gold retirement account holds IRS-approved bullion (.995+ fineness) in an insured, non-bank depository under an authorized custodian, granting pre-tax or Roth growth. Conversely, direct physical ownership offers unencumbered personal possession without custodial overhead, though sales face standard collectible tax rates. Weigh dealer premiums, annual depository fees, and liquidation spreads against your liquidity timeline.
Practical Decision Check
Verify custodian fee transparency, COMEX/LBMA depository insurance standards, dealer buyback spreads, and maintain a disciplined 5% to 10% total portfolio allocation.
Section 1: The Fundamentals of Gold IRAs
A Gold IRA is a self-directed retirement account holding IRS-approved metals (minimum .995 fineness) via a qualified custodian. It offers physical bullion exposure while preserving retirement tax advantages. In contrast, physical gold bought directly provides personal possession but forfeits tax deferral, requiring private storage and insurance. This core distinction defines gold ira vs physical gold.
How the Structures Differ
In a Gold IRA, custodians oversee IRS reporting and secure depository storage. “Home storage” setups violate IRC Section 408(m) rules, triggering disqualification and penalties. For example, a $53,000 IRA allocation secures insured depository vaulting, whereas personally held coins remain ordinary property subject to collectibles capital gains taxes.
Compare custodian fees, dealer spreads, and counterparty risk before choosing an asset structure. A clear comparison appears in this analysis of bullion, ETFs, and mining stocks.
Practical Decision Framework
Clarify your objective: tax deferral, liquidity, or systemic risk protection. Account for annual depository fees ($150–$300), dealer premiums, and Required Minimum Distributions (RMDs). While gold hedges purchasing power, it generates no yields. For context, consult this overview of gold as an investment.
Verify dealer pricing and IRS metal eligibility before transferring rollover funds. Ultimately, a Gold IRA prioritizes tax-sheltered growth under regulated custody, while direct physical gold prioritizes immediate possession and complete autonomy.
| Option | Tax and access | Storage | Best fit |
|---|---|---|---|
| Gold IRA | Tax-advantaged retirement account; withdrawals follow IRA rules | Must be held by an approved custodian | Retirement savers who want metal exposure |
| Physical gold outright | Bought and owned directly; tax treatment depends on sale and use | Stored by you or a third party | Buyers wanting direct possession |
| Home storage gold IRA | Not allowed for standard IRA-held metals | Raises compliance concerns and penalties | Not a proper IRA storage method |
| Direct physical gold storage | Full control, but security is your responsibility | Home safe, vault, or depository | Investors prioritizing access and control |
Section 2: Purchasing Physical Gold: What You Need to Know
When evaluating a gold IRA vs physical gold, assess legal title, depository mandates, and liquidity. Direct purchases grant outright title to specific coins or allocated bars, requiring private vaults and bespoke insurance. In contrast, a precious metals IRA holds IRS-approved bullion through a qualified custodian to maintain tax-deferred or Roth status.
Ownership and security
Direct physical gold provides immediate possession and counterparty-free holding, though bid-ask spreads (typically 2% to 8% over spot) and insured shipping reduce net proceeds upon liquidation. Always verify mint hallmarks, assay certifications, minimum fineness, and vendor buyback spreads. This gold bar buying guide outlines practical verification protocols, such as reconciling serial numbers against purchase invoices.
Retirement account considerations
A self-directed gold IRA requires strict adherence to IRC Section 408(m) purity standards (.995 minimum fineness, with an exception for .9167 American Eagles). Liquidations prior to age 59½ trigger ordinary income tax plus a 10% penalty. To evaluate carrying costs, compare recurring custodial maintenance and segregated vault fees against paper alternatives; the SEC’s ETF overview details how grantor trust structures diverge from titled bullion.
Audit custodial fee schedules, verify storage at an IRS-approved depository, and avoid non-compliant “home storage IRA” LLC structures that risk account disqualification. Direct ownership serves investors prioritizing physical possession and crisis liquidity, whereas a self-directed IRA optimizes tax-advantaged retirement wealth preservation.
Section 3: Tax Implications of Gold Investments
Tax Treatment Basics
Tax treatment depends directly on custody structure. Physical bullion held personally is classified by the IRS as a collectible. Gains on metals held over one year incur a maximum 28% long-term collectibles tax rate, rather than standard 15% or 20% capital gains rates. Short-term holdings sold within a year are taxed at ordinary income rates.
Account Versus Personal Ownership
Holding bullion inside a retirement structure alters this framework. A self-directed IRA functions as a tax-advantaged vehicle, as outlined in this IRA overview. Traditional account growth is tax-deferred, bypassing the 28% collectibles rate until distributions are taxed as ordinary income upon withdrawal.
When comparing gold IRA vs physical gold, strict IRS custody mandates apply. Taking personal possession of SDIRA bullion constitutes an unapproved distribution, triggering ordinary income taxes and a 10% penalty before age 59½. Always review depository gold IRA rules before executing rollovers or transfers.
Practical Steps for Investors
Maintain purchase invoices, settlement sheets, and Form 1099-B records to establish an accurate cost basis. Factor in recurring custodian maintenance, depository vaulting fees, and future Required Minimum Distributions (RMDs). Consult a CPA regarding state bullion sales-tax exemptions and whether Traditional or Roth structures optimize your net returns.
Section 4: Storage Solutions: Protecting Your Gold Assets
Storage architecture dictates the operational trade-offs in gold ira vs physical gold: an IRA mandates third-party depository custody under IRS rules, whereas direct ownership provides immediate physical possession. Each path carries distinct implications for all-risk insurance, liquidity access, carrying costs, and tax liability. Aligning your choice requires evaluating counterparty exposure against personal custody risks.
Choose the Right Structure
Self-directed gold IRAs require IRS-approved, non-bank custodians and UL Class 3 depositories equipped with 24/7 biometric security and comprehensive vault insurance. “Home storage IRAs” violate IRC Section 408(m), triggering immediate taxation and early withdrawal penalties. The IRS clarifies custody mandates in its retirement plans FAQ. When evaluating depositories, factor in flat versus scaled storage fees, segregated versus commingled allocation, and shipping costs.
Protect Access and Value
For direct physical holdings, private home safes (rated UL RSC or higher) or private vaults offer sovereignty, though bank safe deposit boxes lack FDIC insurance for bullion. For retirement accounts, check the eligible precious metals list to confirm minimum fineness requirements (.995 for gold bars and rounds). Ensure all holdings include specific bar serial numbers, assay certificates, and up-to-date insurance riders to maintain title integrity and liquidity.
Takeaway: Balance sovereign control against institutional security by verifying compliance, insurance policies, and depository custody terms.
Conclusion: Making the Right Choice for Your Retirement Portfolio
Choosing with Purpose
Deciding between a gold ira vs physical gold depends on your tax structure and liquidity targets. A self-directed precious metals IRA grants tax-deferred or tax-free growth (IRC Section 408) via IRS-approved depository storage, whereas holding physical bullion directly provides immediate possession without custodial oversight or distribution restrictions. To optimize asset allocation and avoid tax penalties, speak with retirement specialists before allocating capital.
Evaluate the Details
Assess total cost factors, including custodial maintenance, segregated storage fees, and dealer bid-ask spreads. Ensure any IRA bullion meets IRS fineness standards (minimum 0.995 for gold). Avoid non-compliant “home storage” IRA schemes, which trigger immediate taxable distributions and early-withdrawal penalties under IRS audit rules.
Apply a Long-Term View
Align physical precious metals with your broader wealth preservation strategy, rebalancing holdings periodically as retirement horizon, required minimum distributions (RMDs), and macro market conditions dictate.
Frequently Asked Questions
What are the main tax differences between a Gold IRA and buying physical gold?
A Gold IRA offers tax-deferred growth (Traditional) or tax-free withdrawals (Roth) on your gold investments. Physical gold purchased outright is subject to capital gains tax when sold, and potentially sales tax upon purchase depending on your location.
How does storage differ for a Gold IRA versus physical gold?
Gold in a Gold IRA must be stored by an IRS-approved custodian in a secure, insured depository. Physical gold bought outright can be stored at home, in a safe deposit box, or through private vaults, giving you more direct control over its location.
Is it easier to access physical gold or gold held in a Gold IRA?
Physical gold offers immediate access as it’s directly in your possession or readily accessible. Gold in a Gold IRA requires you to follow IRA withdrawal rules and procedures, which can involve custodian processing times and potential penalties if withdrawn before age 59½.
What types of gold are eligible for a Gold IRA?
Only specific types of gold, such as American Gold Eagles, Canadian Gold Maple Leafs, and certain gold bars with a minimum fineness of .995, are eligible for a Gold IRA. Collectible or numismatic coins are generally not permitted.