Table of Contents
- Introduction: Understanding the Role of Precious Metals IRAs in Modern Retirement Portfolios
- What is a Self-Directed Precious Metals IRA?
- Core advantages: Inflation hedging, dollar diversification, and downside risk protection
- IRS regulatory framework and statutory authority overview
- IRS Compliance Rules: Purity Requirements, Custodians, and Storage Mandates
- Strict IRS fineness and purity standards for gold, silver, platinum, and palladium
- The mandatory role of qualified IRS-approved custodians and legal duties
- Storage requirements: Segregated vs. non-segregated vaulting at IRS-approved depositories
- The “home storage” trap: IRS penalties, disqualified transactions, and legal risks
- Comprehensive Breakdown of Eligible Precious Metals vs. Ineligible Assets
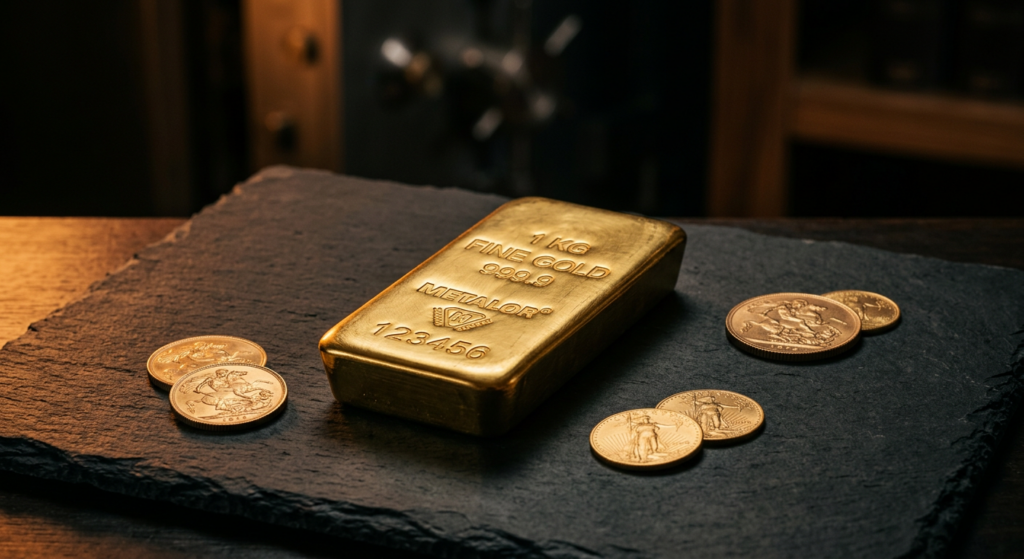
- Eligible gold coins and bullion bars (American Eagles, Canadian Maple Leafs, certified bars)
- Qualifying silver, platinum, and palladium products meeting IRS purity thresholds
- Ineligible items: Rare coins, collectibles, numismatics, and non-conforming bullion
- Proof coins and special editions: Rules, exceptions, and IRS scrutiny
- The Complete Fee Breakdown: Direct Costs, Ongoing Overhead, and Hidden Charges
- One-time setup and account establishment fees
- Annual custodian maintenance and administrative costs
- Depository storage fees (Flat rate vs. scaled percentage pricing) and liability insurance
- Dealer spreads, markups, cash-out costs, and liquidation friction
- Strategic Execution: Step-by-Step Rollovers, Account Funding, and Distributions
- Tax-free 401(k)/IRA rollovers vs. direct trustee-to-trustee transfers
- Purchasing approved physical metal: Execution, secure transit, and vault deposit process
- Managing distributions in retirement: Physical in-kind delivery vs. cash liquidation
- Required Minimum Distributions (RMDs) compliance for physical metal holdings
- Conclusion: Strategic Asset Allocation and Due Diligence Checklist
- Determining the right allocation percentage for precious metals in a balanced portfolio
- Due diligence checklist for selecting trustworthy custodians, depositories, and dealers
- Frequently Asked Questions
Introduction: Understanding the Role of Precious Metals IRAs in Modern Retirement Portfolios
Diversifying beyond conventional stocks and bonds has become a core component of long-term retirement stability rather than a niche strategy. A precious metals IRA allows investors to hold IRS-approved gold, silver, platinum, and palladium within a tax-advantaged retirement account, providing a hedge against inflation and currency devaluation that paper assets alone cannot offer. Unlike traditional IRAs limited to stocks, bonds, and mutual funds, this self-directed structure holds physical bullion meeting minimum purity standards, such as .995 fineness for gold, stored in an IRS-approved depository. A Opulent Gold Group specialist can walk you through custodian requirements, eligible metals, and rollover procedures so you understand exactly how physical bullion functions as a tangible safe haven within your broader portfolio.
What is a Self-Directed Precious Metals IRA?
How It Works
A self-directed precious metals IRA is a retirement account that lets you hold physical gold, silver, platinum, and palladium bullion or coins meeting IRS purity standards, such as gold at 99.5% fineness and silver at 99.9%, as a hedge against inflation and currency devaluation. Unlike conventional IRAs limited to stocks, bonds, and mutual funds, this structure grants direct ownership of the metals themselves, held in an IRS-approved depository on your behalf. For a detailed comparison against paper-based mutual fund IRAs, see our trusted guide. The foundational IRA concept, including contribution limits and tax treatment, is detailed in this widely referenced resource.
Core advantages: Inflation hedging, dollar diversification, and downside risk protection
Why Precious Metals Excel
A qualified precious metals guide explains how these assets preserved value during inflationary periods like the 1970s. Physical gold and silver in a precious metals IRA hedge equity market declines.
Portfolio Stability
Diversifying into a precious metals IRA reduces dollar exposure and equity correlation, cushioning value during downturns. Follow official IRS rules for IRAs to maintain tax advantages, including purity and storage standards. Physical metals serve as a stabilizing anchor.
IRS regulatory framework and statutory authority overview
Statutory Authority Under IRC Section 408
The IRS derives its regulatory authority from Internal Revenue Code Section 408(m), which defines permissible assets for self-directed retirement accounts and specifically exempts certain bullion and coins from the general collectibles prohibition. Authoritative IRS guidance confirms that gold meeting 99.5% purity, silver at 99.9%, and platinum or palladium at 99.95% qualify when held by an IRS-approved trustee or custodian rather than the account owner directly. For those establishing a precious metals ira, these purity thresholds, third-party depository storage requirements, and annual fair market value reporting obligations all apply and cannot be waived. The Gold IRA rollover process must follow these statutory rules precisely, since taking personal possession of the metals or using a non-approved custodian triggers immediate distribution treatment and associated tax penalties.
IRS Compliance Rules: Purity Requirements, Custodians, and Storage Mandates
The Internal Revenue Service strictly regulates physical asset holdings inside a precious metals IRA. Under IRC Section 408(m)(3), bullion must meet specific fineness standards: 99.5% for gold, 99.9% for silver, and 99.95% for platinum and palladium. American Gold Eagle coins are a notable exception, permitted despite falling slightly below the 99.5% threshold. Outside of this named exception, any coin or bar failing to meet these purity levels cannot be held in a retirement account, regardless of its market value or collectibility.
Approved Custodians and Depositories
You cannot personally store the metals in a precious metals IRA, nor can you keep them in a home safe or bank safety deposit box. A qualified, IRS-approved custodian must administer the account, handle all purchase and sale transactions, and coordinate directly with a secure third-party depository on your behalf. Custodial fees typically range from $75 to $300 annually, depending on account size and the specific institution. Understanding this chain of custody, and vetting your custodian’s track record before transferring funds, is essential before funding an account. For a deeper look at compliance specifics, review this comprehensive Gold IRA rules and regulations guide.
Understanding Storage Mandates
Taking physical possession of IRA-held metals constitutes a prohibited transaction, triggering immediate taxation on the full account value plus a potential 10% early withdrawal penalty if you’re under 59½. Approved depositories offer two storage options: segregated vaulting, where your specific coins and bars are kept separately and identifiable as yours, or commingled storage, where assets are pooled with other investors’ holdings of the same type. Segregated storage typically costs more but provides clearer chain-of-title documentation. This third-party storage structure, entirely independent of the account holder, is what preserves the tax-advantaged status of your gold as a tangible asset within the IRA.
Strict IRS fineness and purity standards for gold, silver, platinum, and palladium
Essential Purity Requirements
To be held in a self-directed retirement account, physical precious metal bullion must meet strict fineness standards set by the IRS under 26 U.S.C. § 408(m)(3). Gold must be at least 99.5% pure (.995 fineness), silver 99.9% fine (.999), while platinum and palladium both require 99.95% purity (.9995). Familiarizing yourself with these benchmarks is fundamental before establishing a precious metals IRA, since custodians will reject any coin or bar that fails to meet the required fineness, regardless of its face value or popularity.
Recognizing Approved Products
Only specific minted products satisfy these thresholds. The American Gold Eagle is the sole statutory exception: at 91.67% purity (22-karat), it falls well below the standard 99.5% requirement, yet Congress specifically named it IRS-eligible by law. Most other approved coins clear the bar with room to spare. The Canadian Maple Leaf, for instance, is struck at 99.99% fineness, and the American Silver Eagle meets the .999 silver standard outright. Collectible or numismatic coins graded for rarity, condition, or mintage almost never qualify, since their value comes from scarcity rather than metal content. Always confirm the exact fineness stamped on the product and its melt value before adding any coin or bar to your account.
The mandatory role of qualified IRS-approved custodians and legal duties
Custodian Requirement
Federal law under IRC Section 408(m) requires that a precious metals ira be held by an IRS-approved custodian, typically a bank, trust company, or non-bank trustee specifically licensed to administer self-directed IRAs. Details on distribution rules and account structure are outlined in Publication 590-B.
Custodian Duties
The custodian executes purchases, arranges storage at an approved depository, and files annual reporting (Form 5498) with the IRS; account holders never take physical possession of the metals while funds remain in the IRA. Our physical gold vs ETFs comparison breaks down why this custodian-held structure differs from owning bullion or ETF shares directly. Legally, the custodian holds title to the assets on your behalf, which keeps the account compliant and blocks prohibited transactions like personal storage or self-dealing. Skipping this structure, even briefly, can trigger a taxable distribution and penalties. There’s no workaround here.
Storage requirements: Segregated vs. non-segregated vaulting at IRS-approved depositories
Understanding Custodial Storage Rules
Physical metals held in a precious metals IRA must be stored at an IRS-approved depository under IRC Section 408(m). This isn’t optional—storing coins or bars yourself, even in a home safe, triggers a distribution and disqualifies the account’s tax-advantaged status. Approved depositories typically hold Class 3 vault ratings and carry insurance through providers like Lloyd’s of London. The facility you choose will offer two distinct approaches to how your metals are held.
Segregated vs. Non-Segregated Vaulting
With segregated storage, your specific coins or bars are isolated, tagged, and stored in a dedicated space separate from other clients’ holdings. You maintain direct ownership of those exact serial-numbered items, and audits can verify your specific assets on demand. Non-segregated (commingled) storage pools your holdings with identical assets from other investors—so you own a claim to, say, ten 1-oz American Gold Eagles rather than ten specific coins with tracked serial numbers. Commingling typically cuts annual storage fees by 20-30%, but segregated vaulting gives you unambiguous title to particular pieces. Custodial and depository requirements are governed by IRS guidelines on IRA compliance, which mandate an approved non-bank trustee or depository regardless of which storage method you select.
Choosing the Right Approach
Segregated storage makes sense if you plan to eventually take an in-kind distribution of specific bars or coins, or if precise chain-of-custody matters more to you than shaving a few dollars off annual fees. This distinction becomes especially relevant when transferring existing retirement funds—review our 403(b) or TSP into a Gold IRA rollover guide to understand how storage selections apply during account transitions.
The “home storage” trap: IRS penalties, disqualified transactions, and legal risks
The Trap
Taking physical possession of IRA-owned gold—storing it in a home safe or safety deposit box—triggers an immediate taxable distribution under IRS rules. The IRS treats this as a full distribution of the account’s value, not just the metal removed. A precious metals IRA must use an IRS-approved depository; personal possession means ordinary income tax on the distribution, a 10% early withdrawal penalty if you’re under 59½, and potential disqualification of the entire account, not just the affected assets.
Compliance
Avoid the home storage trap entirely by working only with IRS-approved custodians and depositories—no exceptions, regardless of what “checkbook IRA” promoters claim. Our diversifying your retirement portfolio with metals guide covers proper account structuring, depository selection, and documentation requirements to keep your precious metals IRA compliant and penalty-free.
Comprehensive Breakdown of Eligible Precious Metals vs. Ineligible Assets
Eligible Precious Metals
The IRS sets strict fineness requirements for a precious metals IRA under IRC Section 408(m): gold must be at least .995 pure, silver .999, and platinum or palladium .9995. Acceptable products include American Gold Eagles (permitted by statutory exception despite .9167 fineness) and Canadian Maple Leafs, along with bars from approved refiners like PAMP Suisse or Credit Suisse. Rare or numismatic coins are excluded, regardless of metal content. For comparing choices, review our gold vs silver vs platinum IRAs guide.
Ineligible Assets
Stocks, mutual funds, and conventional real estate don’t qualify for a precious metals IRA since the account is designed to hold physical bullion, not paper assets. A self-directed IRA permits ownership of physical metals meeting IRS fineness standards, but it still excludes collectibles such as rare coins, jewelry, and pre-1933 numismatic gold, per IRC Section 408(m)(2).
Eligible gold coins and bullion bars (American Eagles, Canadian Maple Leafs, certified bars)
Qualifying Government Coins
American Eagle coins qualify for a precious metals IRA under IRC Section 408(m)(3) even though they’re only .9167 fine (22-karat gold) — they’re a specific statutory exception to the standard .995 minimum purity rule. Canadian Maple Leafs and American Buffalo coins, by contrast, meet the .9999 fine gold standard outright. Whichever coin you choose, it must be uncirculated and in its original mint packaging to qualify.
Certified Bullion Bars
Bullion bars must meet a .995 minimum fineness for gold (.999 for silver, .9995 for platinum and palladium) and come from a COMEX/NYMEX-approved refiner or accredited national mint. They also have to be held with an IRS-approved custodian at an approved depository — home storage isn’t an option for IRA-held metals. The custodian handles chain-of-custody verification, authentication, and the required IRS reporting.
Qualifying silver, platinum, and palladium products meeting IRS purity thresholds
Purity Requirements
The IRS sets clear purity thresholds for qualifying retirement account metals under IRC Section 408(m)(3). Silver must reach 0.999 fineness (99.9% pure), while platinum and palladium both require stricter 0.9995 purity levels (99.95% pure). The one notable exception is the American Silver Eagle coin, which qualifies despite technically falling under the standard 0.999 threshold due to its explicit statutory approval.
Approved Products
Eligible products include government-minted coins like the Canadian Platinum Maple Leaf and American Palladium Eagle, plus COMEX-approved bars from accredited refiners such as PAMP Suisse, Johnson Matthey, and Credit Suisse. These assets must carry proper assay certification and meet fineness standards to reside within a precious metals ira without triggering disqualification.
Compliance Importance
Proper qualification ensures alignment with IRS guidance relevant to IRA distributions, protecting investors from tax penalties and potential disqualification. Custodians typically verify refiner accreditation and fineness documentation before accepting metals into a self-directed account, so confirming these details upfront with your dealer prevents costly compliance issues down the line.
Ineligible items: Rare coins, collectibles, numismatics, and non-conforming bullion
What the IRS Disallows
When building a precious metals IRA, you must avoid rare coins, collectibles, and numismatic pieces. Under IRS Publication 590-A and IRC Section 408(m), retirement accounts can only hold bullion meeting strict minimum fineness: .995 for gold, .999 for silver, and .9995 for platinum and palladium. Numismatic and collectible coins are excluded regardless of metal content because their value is driven by rarity, condition, and market demand for collectors rather than by the metal itself—American Rarities and pre-1933 gold coins are common examples that fail this test. Non-conforming bullion is equally prohibited: bars or rounds that fall below the required fineness, or that come from refiners not accredited by NYMEX, COMEX, or a national mint, cannot be held in the account. Custodians will reject any product lacking proper assay certification or refiner hallmarks. Stick exclusively to approved gold, silver, platinum, and palladium coins and bars produced by accredited manufacturers and meeting these minimum fineness thresholds.
Proof coins and special editions: Rules, exceptions, and IRS scrutiny
IRS Rules for Proof Coins
Under Internal Revenue Code Section 408(m), IRA-eligible precious metals must meet minimum fineness standards: .999 for silver, .995 for gold, and .9995 for platinum and palladium. Proof coins are treated differently than standard bullion, so custodians cross-reference each coin against the IRS-approved list before accepting it into a precious metals IRA. American Eagle proof coins are specifically named in the statute and qualify regardless of their proof finish. Commemorative issues and limited special editions, even from the U.S. Mint, generally fail to meet these criteria and are excluded from IRA custody.
Scrutiny on Collectibles
Because proof coins carry premiums tied to condition and mintage rather than metal content, the IRS classifies most of them as collectibles under Section 408(m)(2), which triggers distribution penalties if held improperly in an IRA. American Buffalo coins are the exception worth noting: struck in .9999 fine gold and issued as legal tender, they qualify for IRA inclusion in both bullion and proof formats. Before purchasing any proof coin for a retirement account, verify it against your custodian’s approved mint list to confirm eligibility and avoid triggering a prohibited transaction.
The Complete Fee Breakdown: Direct Costs, Ongoing Overhead, and Hidden Charges
Direct Costs and Setup Fees
Opening a self-directed precious metals IRA typically triggers a one-time custodian setup fee ranging from $50 to $100, though some custodians waive this for larger initial deposits. Expect to also cover first-year storage fees (often $100–$150) and an account application charge, which vary depending on whether you choose segregated or commingled storage.
Ongoing Overhead and Hidden Charges
Beyond setup, annual maintenance fees ($75–$300), storage costs, and insurance premiums add up over the life of the account. Per IRS guidelines for precious metals IRAs, custodians must use approved depositories, which adds cost transparency but also fixed overhead. Watch closely for transaction fees on buys and sells, wire transfer charges, and liquidation fees—these can range from 1% to 5% per transaction and quietly erode long-term returns if not compared across providers before opening an account.
One-time setup and account establishment fees
Typical One-Time Costs
Opening a precious metals IRA typically involves a setup fee ranging from $50 to $150, charged once by the custodian at account opening. This covers new account creation, IRS reporting registration, and processing the paperwork needed to establish your self-directed IRA structure.
Ensuring IRS Compliance
A portion of this fee funds the custodian’s compliance review, confirming your intended holdings meet IRS purity standards before any purchase is approved. IRS Notice 98-8 (PDF) sets the minimum fineness requirements, such as .995 for gold and .999 for silver, that custodians use to verify authenticity and eligibility. Skipping this step risks purchasing bullion that disqualifies your account from tax-advantaged status.
Worth the Investment
A one-time fee of $50 to $150 is a minor cost against the multi-year horizon most investors hold these accounts for. Compared to the cumulative annual storage and custodian fees paid over 10 to 20 years, this upfront charge represents a small fraction of total ownership costs while securing proper IRS-compliant structuring from day one.
Annual custodian maintenance and administrative costs
Understanding the Cost Structure
Every precious metals IRA carries annual custodian maintenance and administrative fees, typically ranging from $75 to $300, that cover account management, record-keeping, and IRS-mandated tax reporting like Form 5498. These recurring charges are separate from one-time setup or transaction fees you pay when funding the account or purchasing metals. For physical bullion and coins, you’ll also pay storage fees to the depository, generally $100 to $200 annually, with segregated vaulting costing more than commingled storage since your metals are kept separately rather than pooled with other investors’ holdings. Some custodians charge flat annual fees regardless of account size, while others scale fees as a percentage of assets, so request a complete fee schedule upfront and calculate total yearly costs before selecting a custodian.
Depository storage fees (Flat rate vs. scaled percentage pricing) and liability insurance
Comparing Flat Fees and Scaled Pricing
Storage costs compound over time, so the fee structure you choose for a precious metals IRA directly affects your long-term returns. Depositories typically charge either a flat annual fee, often between $100 and $300 regardless of holdings value, or a scaled percentage, usually 0.5% to 1% of the asset’s market value. Flat rates work better for larger accounts since costs stay fixed as your portfolio grows, while percentage-based fees favor smaller accounts but become costlier as holdings appreciate. Beyond the fee model, confirm the depository carries all-risk liability insurance that fully covers your metals at current market value, not just a fraction of it. Before committing to a custodian, review the self-directed IRA risks outlined by regulators to avoid providers with inadequate coverage limits or undisclosed administrative charges.
Dealer spreads, markups, cash-out costs, and liquidation friction
Dealer Spreads and Markups
When you buy gold for a precious metals IRA, dealers charge a spread between the spot price and their selling price, typically 3% to 8% for bullion coins and bars, with premiums running higher on limited-mintage or numismatic products. This spread, plus any added dealer markup, is an immediate cost you absorb the moment you purchase, meaning your metal must appreciate past that premium just to break even. Wikipedia’s definition of markup in economics explains this premium in more general terms.
Cash-Out Costs and Friction
When you sell, cash-out costs include buyback spreads that run 2% to 5% below spot, shipping and insurance fees for returning metal to a dealer or depository, and liquidation friction—processing delays of several days to weeks and price uncertainty if spot moves against you before the sale settles. These combined costs reduce your net proceeds below the quoted spot price at the time you decide to sell.
Strategic Execution: Step-by-Step Rollovers, Account Funding, and Distributions
Execution Steps
Request a direct trustee-to-trustee transfer from your existing IRA custodian into a self-directed precious metals IRA; this avoids the 20% mandatory withholding and 60-day rollover deadline that apply to indirect rollovers. Once funds settle, purchase IRS-approved bullion meeting minimum fineness standards (99.5% for gold, 99.9% for silver) and have it shipped directly to an IRS-approved depository—home storage disqualifies the account. When planning distributions, factor in illiquidity and cash-out friction, since liquidating physical metal can take days to settle and often involves dealer spreads that reduce net proceeds—plan withdrawals well ahead of RMD deadlines.
Tax-free 401(k)/IRA rollovers vs. direct trustee-to-trustee transfers
Rollovers
A rollover moves funds from a 401(k) or existing IRA into a new precious metals IRA. The custodian issues a check made out to you, and you have 60 days from receipt to deposit the full amount into the new account or the IRS treats it as a taxable distribution, plus a 10% early withdrawal penalty if you’re under 59½. Note that you’re limited to one indirect rollover per 12-month period across all your IRAs, regardless of how many accounts you hold. Given these constraints, most custodians and financial advisors recommend a direct transfer instead whenever possible.
Transfers
A direct trustee-to-trustee transfer moves assets straight from your current custodian to the new precious metals IRA custodian, with funds never passing through your hands. This removes both the 60-day deadline and the once-per-year rollover limit, since transfers aren’t subject to either rule. For investors diversifying into physical gold or silver, this method also avoids withholding requirements that can apply to rollover checks, making it the more reliable option for funding the account without triggering unintended tax consequences.
Purchasing approved physical metal: Execution, secure transit, and vault deposit process
Funding and Purchase Execution
Your custodian executes the buy order using funds already held in your precious metals IRA, typically sourced via a direct rollover from an existing 401(k) or traditional IRA. To preserve tax deferral and avoid the 10% early withdrawal penalty, the transfer must be completed as a trustee-to-trustee transfer, meaning funds move directly between custodians and never pass through your hands. This distinction matters: an indirect rollover gives you only 60 days to redeposit funds before triggering taxes and penalties, while a direct transfer carries no such deadline.
Secure Transit and Vault Deposit
Once purchased, the metals ship via fully insured, discreet carriers—typically Brink’s or a similar bonded logistics provider—to an IRS-approved depository such as Delaware Depository or Brink’s Global Services. Upon arrival, the vault verifies purity against IRS fineness requirements (99.5% for gold, 99.9% for silver) and confirms exact weight against the invoice. The bars or coins are then placed into your allocated, segregated storage account, physically separated from other investors’ holdings rather than commingled, and covered under the depository’s insurance policy. Your custodian receives a detailed deposit receipt confirming serial numbers, weights, and storage location, which becomes part of your permanent account records for your precious metals IRA.
Managing distributions in retirement: Physical in-kind delivery vs. cash liquidation
Taking Physical Possession vs. Selling for Cash
When taking distributions from a precious metals ira, you face a critical choice. You can request an in-kind distribution, having the custodian ship your actual bullion coins or bars directly to you, or you can instruct the custodian to liquidate the metals at the current spot price and wire cash to your bank account. In-kind delivery avoids dealer spreads and liquidation fees, but you become responsible for secure storage, insurance, and, if you’re under 59½, the logistics of paying any 10% early withdrawal penalty out of pocket since no cash is generated. A cash distribution is administratively simpler and covers taxes automatically through withholding, but it locks in a sale price you don’t control and ends your exposure to further metal appreciation. Either way, the distribution’s fair market value is taxed as ordinary income in the year received, and once you reach age 73, required minimum distributions apply just as with any other traditional IRA. Review the potential tax consequences with your custodian before choosing a distribution method.
Required Minimum Distributions (RMDs) compliance for physical metal holdings
RMD Rules for Physical Metals
The Required Minimum Distributions (RMDs) rules apply to a precious metals IRA the same way they apply to any other traditional IRA. Under current SECURE 2.0 rules, you must begin withdrawals at age 73 if you were born between 1951 and 1959, or age 75 if you were born in 1960 or later. You can satisfy the RMD with an in-kind distribution of the actual coins or bars, or by liquidating a portion of the metal and distributing cash. Either way, the custodian needs an accurate valuation on file before the distribution is processed.
Valuation and Compliance
RMDs on physical metal are calculated using the spot price on the valuation date, not the original purchase price, so your custodian will need current market pricing from your depository or dealer. If you take an in-kind distribution, get a dated appraisal or dealer quote to support the reported fair market value in case of an IRS inquiry. Missing an RMD deadline triggers a 25% excise tax on the shortfall, though this drops to 10% if you correct the error within two years. Coordinate with your custodian well before year-end to confirm valuations, avoid last-minute liquidation costs, and stay compliant.
Conclusion: Strategic Asset Allocation and Due Diligence Checklist
Strategic Allocation Review
Most advisors recommend limiting precious metals ira holdings to 5-15% of total retirement assets, using physical gold and silver to hedge against inflation and equity market drawdowns rather than as a primary growth vehicle. Review your allocation annually or after moves of 10% or more in metals prices, rebalancing back to your target percentages to keep the portfolio aligned with your risk tolerance and time horizon.
Due Diligence Essentials
Confirm your custodian holds proper IRS approval and check third-party ratings before transferring funds. Compare storage fees, annual maintenance charges, and dealer markups across at least three providers, since these costs vary significantly and compound over decades. Review authoritative IRS guidance on contribution limits, purity standards, and prohibited transactions before funding your account.
Determining the right allocation percentage for precious metals in a balanced portfolio
Factors Influencing Allocation
Your ideal allocation within a precious metals IRA depends on risk tolerance, time horizon, and broader economic conditions. Conservative investors might allocate 5-10% of retirement assets, treating gold and silver strictly as a hedge against market downturns. Conversely, investors with a higher risk appetite, seeking deeper portfolio diversification, could consider up to 15-20%. Age is a critical factor: investors in their 30s and 40s can often weather short-term price volatility, while those within five to ten years of retirement typically prefer the greater stability that a smaller, more conservative allocation provides.
A Practical Range for Balance
Most financial analysts and retirement planners suggest a moderate precious metals IRA allocation between 5% and 10% of total portfolio value. This range has historically been sufficient to buffer against inflation and currency devaluation without introducing excessive price swings into an otherwise stock-and-bond-heavy portfolio. A key takeaway for anyone opening a precious metals IRA: the objective is insurance against systemic risk, not a vehicle for speculative gains, so resist the temptation to over-concentrate holdings beyond what your overall risk profile supports.
Due diligence checklist for selecting trustworthy custodians, depositories, and dealers
Due Diligence Essentials
When evaluating custodians and depositories for a precious metals IRA, prioritize these key checks:
- Verify IRS-approved status under 26 CFR 1.408-2(e) and confirm recent independent audits (SOC 1 or SOC 2 reports).
- Confirm comprehensive insurance coverage, typically through Lloyd’s of London syndicates, and require segregated, allocated storage rather than commingled holdings.
- Assess dealer reputation through BBB ratings, Trustpilot reviews, and a minimum of five years in operation.
For tailored advice, schedule a consultation with our specialists.
Frequently Asked Questions
What precious metals are eligible for a self-directed IRA?
To qualify for an IRA, gold must be 99.5% pure, silver must be 99.9% pure, and platinum and palladium must be 99.95% pure. These eligible metals must be held in the form of approved bullion bars or specific sovereign coins, like the American Eagle.
Can I store my Precious Metals IRA gold at home?
No, IRS regulations strictly prohibit storing IRA-approved precious metals at home. All physical metals must be held securely in an IRS-approved vault or depository to maintain their tax-advantaged status and avoid severe tax penalties.
What are the typical costs and fees of a Precious Metals IRA?
You can expect to pay one-time account setup fees, annual custodian administrative fees, and secure storage fees charged by the depository. Additionally, bullion dealers typically charge a markup or premium above the market spot price of the metals at the time of purchase.
How do you fund or roll over a Precious Metals IRA?
You can fund your account through standard annual contributions, or by executing a tax-free rollover or transfer from an existing retirement account, such as a traditional IRA, 401(k), or 403(b). Once the funds settle, your custodian will purchase your chosen eligible metals from an authorized dealer.