Table of Contents
- 1. Introduction: Safeguarding Your Retirement Portfolio with a Gold IRA Rollover
- – Understanding Precious Metals IRAs and Their Role in Wealth Preservation
- – Key Economic Drivers: Inflation Hedging, Stock Market Volatility, and Dollar Protection
- – Assessing Eligibility: Who Should Consider Converting a 401(k) or Traditional IRA
- – 2. Direct vs. Indirect Rollovers: Navigating IRS Regulations and Tax Implications
- – Direct Trustee-to-Trustee Transfers: The Zero-Tax Risk Method Explained
- – Indirect Rollover Mechanics: The 60-Day Window, 20% Tax Withholding, and Annual Limits
- – Tax Pitfalls and Penalty Avoidance: Preventing Early Distribution Trigger Events
- – 3. Step-by-Step Execution Guide: Securing Your 401(k) or IRA Transfer
- – Step 1: Selecting and Vetting an IRS-Approved Self-Directed IRA (SDIRA) Custodian
- – Step 2: Account Setup, Funding Authorization, and Rollover Execution
- – Step 3: Selecting and Purchasing IRS-Compliant Physical Gold Bullion
- – Step 4: Vault Logistics: Transferring Assets to Authorized Depositories
- – 4. Regulatory Compliance Standards: Approved Metals, Custody, and Storage
- – IRS Purity Requirements: Minimum Fineness Criteria for Gold, Silver, and Platinum
- – Approved Bullion vs. Ineligible Collectibles: Eligible Coins and Bar Formats
- – Depository Storage Rules: Segregated vs. Non-Segregated Storage and the Home Storage Myth
- – 5. Fee Structure Analysis, Scam Prevention, and Strategic Asset Allocation
- – Breaking Down Total Costs: Setup Fees, Annual Custodial Maintenance, and Vault Storage
- – Industry Red Flags: High-Pressure Sales, Overpriced Collectibles, and “Free Silver” Scams
- – Portfolio Architecture: Establishing an Optimal Gold Allocation Percentage for Retirement
- – 6. Conclusion: A Step-by-Step Checklist for a Safe Gold IRA Transition
- – Essential Due Diligence Checklist Before Transferring Retirement Funds
- – Final Action Steps to Initiate Your Tax-Free, Penalty-Free Rollover
- Frequently Asked Questions
1. Introduction: Safeguarding Your Retirement Portfolio with a Gold IRA Rollover
A gold IRA rollover moves funds from an existing 401(k) or traditional IRA into a self-directed account holding physical gold, silver, platinum, or palladium, giving retirement savings a hedge against inflation, market volatility, and overexposure to equities. The IRS permits this through a trustee-to-trustee transfer or a 60-day rollover, though missing that 60-day window triggers taxes and a 10% early withdrawal penalty if you’re under 59½. Precious metals can diversify a portfolio when added strategically; Opulent Gold specialists outline the IRS purity standards, eligible metals, and custodian rules that govern the process.
Assess the Risks
Compare account setup fees, annual storage costs (typically $100-$300), buy-sell spreads, and liquidity timelines before initiating a transfer. Confirm whether the metals must be stored in an IRS-approved depository, since home storage of IRA-owned gold violates federal rules and can disqualify the entire account.
Begin Carefully
Request a written fee schedule and rollover timeline from the custodian, verify their credentials with the Better Business Bureau or state regulators, and consult a fee-only financial adviser before moving any funds.
– Understanding Precious Metals IRAs and Their Role in Wealth Preservation
Core Concept
A gold IRA rollover transfers funds from an existing 401(k) or traditional IRA into a self-directed account holding IRS-approved bullion, typically gold bars or coins meeting 99.5% purity standards. This diversifies retirement savings beyond traditional stocks and bonds. An IRA overview explains the tax-advantaged structure governing these accounts, while qualifying metals must meet specific fineness requirements and be stored in an IRS-approved depository, not held personally.
Preservation in Practice
Investors use gold IRA rollovers to hedge against inflation and currency devaluation, but bullion prices fluctuate significantly and carry no yield, so fees directly impact long-term returns. Before rolling over funds, compare custodial account fees (often $75-$300 annually), storage and insurance costs, and buyback liquidity terms across providers. Required minimum distributions at age 73 apply to gold IRAs just as with traditional retirement accounts, and early withdrawals before 59½ trigger a 10% penalty plus ordinary income tax. The conversion planning guide outlines the transfer steps and documentation involved; always confirm specific tax treatment and rollover eligibility with a qualified financial adviser before initiating the transfer.
– Key Economic Drivers: Inflation Hedging, Stock Market Volatility, and Dollar Protection
Why Gold Matters
Inflation above the Fed’s 2% target steadily erodes purchasing power, and a $100,000 nest egg loses roughly 26% of its real value over 15 years at 2% average inflation. Add stock market volatility and a weakening dollar, and retirement portfolios face compounding pressure from multiple directions. Physical gold has historically moved independently of equities and cash, since its price often rises when the dollar weakens or when investors seek safety during downturns. A gold ira rollover lets you shift a portion of retirement funds into physical bullion within a tax-advantaged structure, but results still hinge on allocation size (typically 5-15% of a portfolio), custodian fees, and personal risk tolerance. Review this 401(k) rollover guide before initiating a transfer.
Practical Safeguards
Compare custodians on annual fees, storage costs, and buyback policies, since these vary significantly between providers. Confirm your gold meets IRS purity standards (99.5% for gold coins and bars) and is held in an approved depository, not at home. Consult the IRS rollover chart to verify which retirement accounts qualify for direct or indirect rollovers without triggering penalties. Key takeaway: diversify deliberately based on your timeline and risk profile, not as a reactive move to market headlines.
– Assessing Eligibility: Who Should Consider Converting a 401(k) or Traditional IRA
Investors considering a gold ira rollover should evaluate five factors: current age relative to the 59½ withdrawal threshold, tax bracket, time horizon to retirement, existing portfolio allocation, and tolerance for precious-metal price swings, which have historically ranged 15-20% annually. A retirement guide can clarify custodian requirements and IRS-approved metal purity standards.
Who May Qualify
Holders of a traditional IRA, SEP IRA, or an eligible 401(k) from a former employer with a 10+ year retirement horizon are typical candidates. Before transferring funds, compare annual custodian fees (often $150-$300), storage costs, bid-ask spreads on physical metals, and any surrender restrictions in your current plan.
Essential Checks
Review IRS distribution rules and confirm the custodian executes a trustee-to-trustee transfer, not a 60-day rollover, to avoid the mandatory 20% withholding and potential early-distribution penalties. Tip: request an itemized cost breakdown covering setup, annual storage, and liquidation fees before signing any transfer paperwork.
– 2. Direct vs. Indirect Rollovers: Navigating IRS Regulations and Tax Implications
Direct Transfers
A direct gold IRA rollover moves funds trustee-to-trustee, so you never take personal possession of the assets. This method avoids the mandatory 20% withholding and sidesteps taxable events entirely, provided the transfer stays within IRS guidelines. Before authorizing the transfer, confirm the receiving custodian is IRS-approved to hold precious metals and that the depository meets IRS purity and storage requirements.
Indirect Transfers
An indirect transfer gives you 60 days from receipt of funds to redeposit the full amount into a qualified account. Miss that window, and the IRS treats the distribution as taxable income, plus a 10% early withdrawal penalty if you’re under 59½. A key pitfall: custodians must withhold 20% for federal taxes on indirect distributions, so you’ll need to cover that shortfall out of pocket to complete a full rollover, or the difference counts as a distribution. Given the tax exposure and tight timeline, most experienced investors default to direct transfers unless there’s a specific reason to take receipt of funds. Since inflation trends often factor into decisions about precious metals allocation, review this inflation planning guide and inflation overview, and consult a qualified tax professional before choosing a transfer method.
– Direct Trustee-to-Trustee Transfers: The Zero-Tax Risk Method Explained
How It Works
A gold ira rollover stays completely tax-free when the custodian moves funds directly to the new custodian via wire transfer or check made payable to the receiving institution, not to you personally. Submit a trustee-to-trustee transfer request, confirm the receiving custodian’s depository accepts IRS-approved bullion (minimum 99.5% purity for gold bars and coins), and retain the transfer confirmation and account statements for your records. Because the funds never touch your bank account, no 1099-R withholding applies and the 60-day rollover clock never starts—eliminating the most common way investors accidentally trigger taxes and penalties.
Practical Safeguards
Confirm every metal purchased meets IRS fineness requirements before the transfer completes, since noncompliant bullion can disqualify the entire IRA; gold’s investment role offers useful context on why diversification matters here, while the 403(b) or TSP conversion guide walks through transfer mechanics for employer-sponsored accounts. The critical rule: never accept a check made out to you directly, even briefly—doing so converts the transaction into a distribution subject to the 60-day deadline and potential 10% early withdrawal penalty if you’re under 59½.
– Indirect Rollover Mechanics: The 60-Day Window, 20% Tax Withholding, and Annual Limits
Timing and Withholding
In an indirect gold IRA rollover, your custodian sends the distribution directly to you rather than to the new trustee. The clock starts the day you receive the funds, and you have exactly 60 days to redeposit the full amount into a qualifying IRA. The IRS requires the payer to withhold 20 percent for taxes upfront, so if you’re moving $50,000, you’ll only receive $40,000 in hand. To complete a full rollover and avoid triggering income tax plus a possible 10 percent early withdrawal penalty on the shortfall, you’ll need to make up that withheld 20 percent from other funds and redeposit the entire original balance.
Limits and Documentation
The IRS permits only one indirect rollover across all your IRAs in any 12-month period, regardless of how many accounts you own. Attempting a second one within that window makes the distribution taxable and potentially subject to penalties. Review the IRS guidance before initiating the transfer, and keep copies of the distribution statement, the 1099-R, and your redeposit confirmation for at least three years in case of an audit. Before funding the new account, confirm the eligible metals list matches what you intend to purchase, since IRA-approved gold must meet minimum fineness requirements and non-compliant bullion can disqualify the entire rollover.
– Tax Pitfalls and Penalty Avoidance: Preventing Early Distribution Trigger Events
Prevent Costly Triggers
Before initiating a gold IRA rollover, confirm your account eligibility, use a direct trustee-to-trustee transfer, and verify the metals meet IRS purity standards. Missing the 60-day window on an indirect rollover or purchasing non-approved collectibles turns the transaction into taxable income plus a 10% early distribution penalty if you’re under 59½.
Build a Compliance Check
- Verify both the custodian and depository carry current IRS approval before funding the account.
- Keep transfer confirmations, account statements, and beneficiary designations on file for at least seven years.
Review IRA distribution rules through retirement plan guidance, then consult this safe bar-buying guide before purchasing bullion. Request written confirmation after each transfer step, and consult a tax advisor promptly whenever your account structure changes or a rollover question arises.
– 3. Step-by-Step Execution Guide: Securing Your 401(k) or IRA Transfer
Confirm the Transfer
Choose a direct trustee-to-trustee gold IRA rollover to avoid the 60-day distribution rule and the mandatory 20% withholding that applies to indirect rollovers. Verify IRS-eligible metals (99.5% purity for gold, 99.9% for silver), custodian fees, and account ownership details before authorizing the move, then cross-check custodian instructions against IRS rollover guidance. Request written confirmation from both custodians and retain transfer statements, signed forms, and delivery records for your tax files.
Secure and Monitor Assets
Confirm the depository is IRS-approved, fully insured, and provides quarterly or annual reporting on your holdings. Use this secure storage guide to evaluate vaulting standards and segregated versus commingled storage options. Review your allocation statement annually, audit custodian fees against your original agreement, and report any discrepancies to the custodian within 30 days. Key takeaway: document every step of the rollover and never take personal possession of the metals during transfer, as this triggers a taxable distribution.
– Step 1: Selecting and Vetting an IRS-Approved Self-Directed IRA (SDIRA) Custodian
Verify the Custodian
Before a gold IRA rollover, confirm the provider is an IRS-approved custodian regulated under 26 U.S.C. 408(a), not merely a metals dealer operating under a custodian’s name. Verify licensing with the state banking authority, compare annual fees (typically $75-$300 for administration plus $100-$300 for storage), and confirm segregated versus commingled storage options with full insurance coverage through the depository. Ask who executes trades, how often statements arrive (monthly or quarterly is standard), and whether the custodian reports directly to the IRS on Form 5498.
Confirm Transfer Procedures
Use a direct trustee-to-trustee transfer rather than a 60-day rollover; a direct transfer avoids the mandatory 20 percent withholding and the risk of missing the 60-day deadline, which triggers taxes and a possible 10 percent early withdrawal penalty. Review IRS rollover guidance before signing any transfer paperwork. Compare account minimums (often $10,000-$25,000), setup and wire fees, and the list of IRS-approved depositories the custodian actually uses. Consult the custodian rules guide to confirm which metals meet IRS purity standards and what documentation the custodian requires to complete the transfer without delays.
– Step 2: Account Setup, Funding Authorization, and Rollover Execution
Open and Authorize
Start your gold ira rollover by selecting an IRS-approved custodian, completing identity verification (W-9, government ID), and signing a transfer authorization form. Confirm annual fees, IRA-eligible metals (99.5% purity gold, 99.9% silver), the depository used for storage, and beneficiary designations before signing anything.
Fund the Account
Choose a direct trustee-to-trustee transfer whenever possible; funds move custodian-to-custodian and you never take possession, eliminating withholding. If you must use an indirect rollover, review the 60-day distribution deadlines closely—missing that window triggers ordinary income tax plus a 10% early withdrawal penalty if you’re under 59½.
Verify Completion
Save all transfer confirmations, verify the custodian received funds and executed the bullion purchase, and check that metals were shipped to the approved depository rather than your home. Reconcile account statements against confirmations within one week to catch discrepancies before they compound.
– Step 3: Selecting and Purchasing IRS-Compliant Physical Gold Bullion
Choose Eligible Bullion
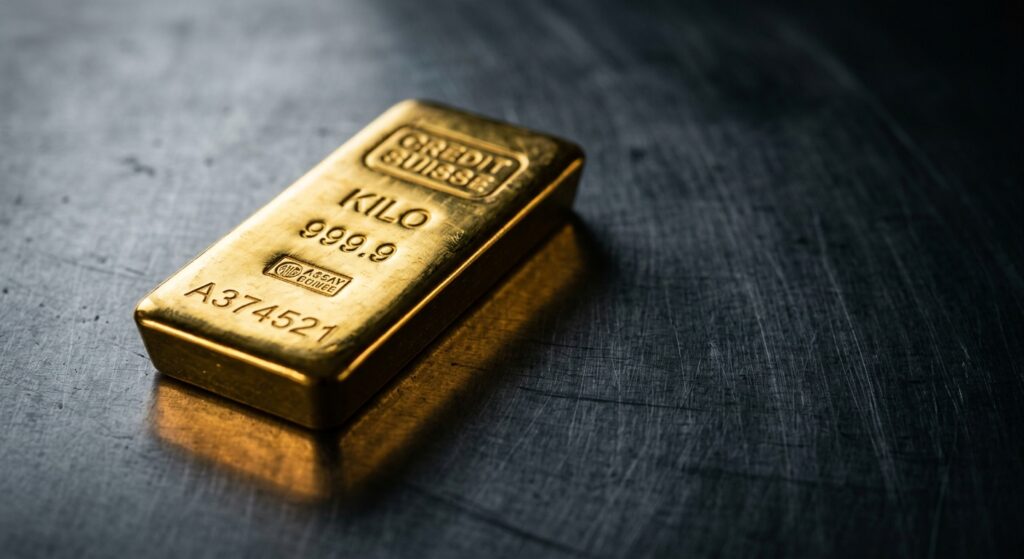
For a gold IRA rollover, the IRS requires bars and rounds to meet a minimum fineness of .995 (99.5% pure gold), per IRC Section 408(m)(3). American Gold Eagle coins are a specific statutory exception, permitted at .9167 fineness despite not meeting this threshold. Stick to products from LBMA-accredited or NYMEX/COMEX-approved refiners like PAMP Suisse, Credit Suisse, or the U.S. Mint. Before ordering, confirm the refinery hallmark, exact weight, and serial number match the assay certificate, and steer clear of proof coins, rare editions, or numismatic pieces, which the IRS classifies as collectibles and disqualifies from IRA holdings.
Verify Purchase and Custody
Compare dealer premiums over spot price (typically 3-8% for bullion bars), annual storage fees, and insurance coverage limits before committing to a purchase. The IRS rollover guidance outlines the 60-day rollover window and mandatory 20% withholding on indirect distributions, so a direct trustee-to-trustee transfer avoids that withholding exposure entirely. Have the dealer ship bullion directly to your approved custodian or depository, never to your home, since personal possession triggers a taxable distribution. Retain all invoices, assay certificates, and chain-of-custody documentation for your records. For most rollovers, a one-ounce .9999 fine gold bar strikes the right balance: it’s easy to price against spot, simple to authenticate, and straightforward to liquidate later without fractional-weight complications.
– Step 4: Vault Logistics: Transferring Assets to Authorized Depositories
After custodian approval, a gold IRA rollover moves funds directly to an IRS-approved depository such as Delaware Depository or Brink’s, never into personal possession. The custodian arranges fully insured armored transport, verifies chain of custody at each handoff, and logs arrival with a time-stamped receipt.
Transfer Controls
Confirm the depository holds COMEX or ICE-approved accreditation, carries all-risk insurance covering full replacement value, and undergoes independent third-party audits at least annually. Verify only IRS-approved metals (99.5% pure gold, 99.9% silver) are accepted. Request a signed shipping receipt and a detailed inventory statement listing bar numbers, refiner marks, and exact weights before wiring funds.
Tax-Safe Completion
Never take physical possession of the metals at any point; use a direct trustee-to-trustee transfer to avoid the 60-day rollover clock and the 10% early withdrawal penalty for account holders under 59½. Review IRS IRA withdrawal rules before signing any transfer paperwork, then retain all confirmations, receipts, and inventory statements securely for at least seven years in case of an audit.
– 4. Regulatory Compliance Standards: Approved Metals, Custody, and Storage
Approved Metals
A compliant gold IRA rollover requires bullion meeting IRS purity standards: gold at 99.5% fine, silver at 99.9%, and platinum or palladium at 99.95%. American Gold Eagles are a notable exception, permitted despite falling below the 99.5% threshold. Proof and collectible coins generally don’t qualify. Confirm eligibility with your custodian before purchase to avoid a distribution penalty.
Custody and Storage
IRS rules require metals to sit with an authorized custodian in an IRS-approved depository, never at home or in a personal safe. Direct trustee-to-trustee transfers avoid the 60-day rollover window and the withholding issues that come with distributions paid to you first; the rollover IRA guidance covers the mechanics of moving funds IRA-to-IRA.
Practical Check
Before funding, request documentation covering metal purity certificates, custodian licensing, storage insurance coverage, third-party audit reports, and the full fee schedule, including storage and transaction fees. Keep copies of all statements and verify the depository’s registration directly rather than relying on the dealer’s representation alone.
– IRS Purity Requirements: Minimum Fineness Criteria for Gold, Silver, and Platinum
IRS Fineness Standards
Under IRC Section 408(m)(3), a gold IRA rollover requires gold bullion to meet a minimum fineness of 0.995 (99.5% pure), silver at 0.999 (99.9%), and platinum at 0.9995 (99.95%). Palladium follows the same 0.9995 standard. One notable exception: American Gold Eagle coins are IRS-approved despite only being 91.67% pure (22 karat), so purity alone doesn’t guarantee eligibility—the product must also appear on the IRS-approved list. Custodians handling a gold IRA rollover will verify these specs before accepting metals into a self-directed account. Review the IRS’s official IRA guidance for the full rollover procedures and timing rules that apply once funds move into the account.
Practical Check
A 24 karat gold bar (99.99% pure) clears the 99.5% threshold with room to spare, and American Gold Eagle coins qualify by IRS exception despite lower purity. Standard 14K or 18K jewelry, however, falls well below the fineness requirement and won’t qualify for a gold IRA rollover, regardless of resale value.
– Approved Bullion vs. Ineligible Collectibles: Eligible Coins and Bar Formats
Approved Bullion
For a gold IRA rollover, choose IRS-approved bullion such as American Gold Eagle coins, Canadian Gold Maple Leaf coins, or bars produced by NYMEX- or COMEX-accredited refiners. IRS rules require gold to reach 99.5 percent purity, though American Gold Eagles are specifically exempted despite their 91.67 percent (22-karat) fineness. Before purchase, confirm each product’s assay certification and request refiner documentation showing the exact fineness stamped on the coin or bar.
What to Exclude
Rare coins, numismatic or graded collectibles, jewelry, and commemorative pieces don’t meet IRA eligibility standards, regardless of gold content. A self-directed IRA requires an IRS-approved custodian and storage in an approved depository, not personal possession. Before wiring any funds, get written eligibility confirmation from your custodian and cross-check the product against the current IRS-approved bullion list.
– Depository Storage Rules: Segregated vs. Non-Segregated Storage and the Home Storage Myth
Storage Models
A gold IRA rollover requires depository storage at an IRS-approved facility, not a home safe or safety deposit box. Segregated storage keeps your specific coins and bars in a dedicated container under your account number, ensuring you receive back the exact items deposited. Non-segregated storage commingles your metals with other clients’ holdings of the same type and purity, though your ownership share remains fully tracked. Both models require third-party custodianship, Lloyd’s of London or comparable insurance coverage, and regular inventory audits.
Practical Rule
The home-storage LLC strategy marketed by some promoters is not a compliant shortcut; the IRS has flagged this arrangement, and personally holding IRA-owned metals can trigger distribution taxes, the 10% early withdrawal penalty, and loss of tax-deferred status. Before funding your account, confirm annual storage fees (typically $100-$300), audit frequency, and withdrawal procedures with your custodian, then review official IRS rollover guidance to verify compliance.
– 5. Fee Structure Analysis, Scam Prevention, and Strategic Asset Allocation
Fees and Fraud Checks
Before completing a gold IRA rollover, compare setup fees (typically $50-$300), annual storage costs (often 0.5%-1% of asset value or a flat $100-$250), trading spreads, and administration charges across custodians. Request a fee schedule in writing, verify the custodian’s credentials with the IRS-approved trustee list, and confirm the depository is IRS-approved for segregated or commingled storage. Avoid any dealer promising guaranteed returns, waived fees for “limited time” offers, or high-pressure tactics to buy specific coins at inflated premiums. Full IRS rules on eligible precious metals assets and rollover procedures appear in IRS Publication 590-A.
Strategic Allocation
Most financial advisors recommend limiting precious metals to 5%-15% of a retirement portfolio, keeping the allocation proportionate to overall risk tolerance rather than concentrating retirement savings in metals alone. For example, an investor nearing retirement might pair a 10% gold and silver allocation with a mix of bond funds and dividend-paying stocks to balance inflation protection against liquidity and growth needs. Rebalance the portfolio annually or when metals prices shift the allocation by more than a few percentage points, review liquidity needs before required minimum distributions begin, and keep documentation of every purchase, transfer, and storage fee for tax reporting purposes.
– Breaking Down Total Costs: Setup Fees, Annual Custodial Maintenance, and Vault Storage
Setup and Annual Fees
A gold IRA rollover typically involves a one-time account setup fee ($50-$100), annual custodial maintenance, and per-transaction charges. Always ask whether fees are flat-rate or asset-based, and get a written fee schedule before transferring funds. The difference matters at scale: a flat $50 annual fee costs the same regardless of balance, while a 0.5% asset-based fee on $100,000 runs $500 per year and keeps growing as your account does.
Vault Storage
Storage costs depend on whether your metals are held segregated (your specific bars/coins, stored separately) or commingled (pooled with other clients’ holdings), plus the insurance coverage level. Segregated storage generally costs more but ensures you receive back the exact items you deposited. Before funding any account, confirm withdrawal and liquidation fees in writing, and review IRS rollover guidance to stay compliant. The practical takeaway: evaluate total annual cost across setup, custody, and storage together, not just a custodian’s introductory-year pricing.
– Industry Red Flags: High-Pressure Sales, Overpriced Collectibles, and “Free Silver” Scams
Spot Pressure Tactics
Be wary when a representative demands an immediate gold IRA rollover, promises guaranteed returns, or discourages independent research. Free silver promotions often mask markups of 30% to 50% over spot price, undisclosed shipping and insurance costs, or a required minimum purchase to qualify. Before transferring funds, request a written fee schedule, buyback terms in writing, and verification of the dealer’s licensing and Better Business Bureau standing.
Verify the Structure
Confirm the custodian holds proper IRS approval, that metals meet minimum fineness requirements (.995 for gold, .999 for silver), and that storage fees, insurance coverage, and segregated versus commingled storage terms are disclosed upfront. This custody overview clarifies custody basics. Get quotes from at least three dealers, compare total cost including markup and annual fees, and walk away if any party can’t clearly explain who holds legal title to your metals.
– Portfolio Architecture: Establishing an Optimal Gold Allocation Percentage for Retirement
Set a Target
A gold IRA rollover should complement, not dominate, retirement savings. Most financial advisors recommend allocating 5 to 10 percent of a portfolio to precious metals, adjusting within that range based on age, income stability, liquidity needs, and risk tolerance. A 30-year-old with decades until retirement might lean toward the lower end, while someone nearing retirement seeking a hedge against inflation might approach 10 percent. Keep stocks, bonds, cash, and metals diversified across the remaining 90 to 95 percent rather than fixating on the metals percentage alone.
Apply the Plan
Review your allocation annually and rebalance whenever gold drifts more than 2 to 3 percentage points above your target, since metals can spike during market stress and quietly become overweight. Confirm eligible bullion meets IRS purity standards before purchasing: gold must be at least 99.5% pure, silver 99.9%, and platinum or palladium 99.95%; fineness measurements explain how these thresholds are calculated and verified. Tip: document your target allocation, custodian fees, storage costs, and required minimum distribution timeline in writing before purchasing, so future rebalancing decisions aren’t made on the fly.
– 6. Conclusion: A Step-by-Step Checklist for a Safe Gold IRA Transition
Final Safety Checklist
A safe gold IRA rollover starts with a written plan: compare custodian fees, confirm IRS-approved storage, and review distribution rules. Check the IRS rollover guidance for transfer timing and 1099-R reporting.
Before You Transfer
- Confirm metal fineness meets IRS purity standards and insurance coverage.
- Use direct trustee-to-trustee transfers to avoid withholding and penalties.
- Keep statements, invoices, and confirmations for tax records.
Review the account annually and rebalance only after weighing costs, liquidity, and retirement goals.
– Essential Due Diligence Checklist Before Transferring Retirement Funds
Verify the Custodian
Before executing a gold IRA rollover, confirm the custodian’s licensing with the IRS and state banking authorities, insurance coverage on stored assets, complete fee schedule, and the specific depository used (typically Delaware Depository or Brink’s). Review IRS IRA guidance for ownership structure and reporting requirements under Form 5498. Request written details on segregated versus commingled storage, third-party audit frequency, and liquidation turnaround times before signing any agreement.
Compare Costs and Transfers
Request itemized setup fees, annual administration charges, storage costs, bid-ask spreads, and termination fees in writing from at least three providers. Run identical dollar-amount scenarios across each to spot markup differences that flat fee sheets often hide. Always choose direct trustee-to-trustee transfer over a 60-day rollover to avoid the mandatory 20% withholding and missed-deadline penalties. Verify beneficiary designations transferred correctly, and retain all transfer confirmations and account statements for at least seven years for tax purposes.
Practical Safeguard
Delay purchasing metals until funds have fully settled in the new account and all terms are documented in writing. Advertised “no-fee” promotions frequently conceal 5-10% premiums over spot price, hidden minimum balance requirements, or restrictive buyback policies that reduce your proceeds at liquidation.
– Final Action Steps to Initiate Your Tax-Free, Penalty-Free Rollover
Confirm Eligibility
Request written confirmation from your custodian that your account qualifies for a gold IRA rollover, verify whether you hold a traditional, Roth, SEP, or 401(k) account, and choose a direct trustee-to-trustee transfer to avoid the mandatory 20% IRS withholding that applies to indirect rollovers. Keep transfer forms, beneficiary designations, and delivery instructions together, and confirm your new custodian accepts the specific account type before initiating the transfer.
Complete Transfer
Review tax treatment for your account type, confirm IRS-approved metals purity standards (99.5% for gold, 99.9% for silver), and verify IRA-approved depository storage arrangements before signing any paperwork. Then speak with a rollover specialist to coordinate timing and ensure funds move within the 60-day window if handling an indirect transfer.
Frequently Asked Questions
What is a Gold IRA rollover?
A Gold IRA rollover is a tax-free process where you transfer funds from an existing retirement account, such as a traditional 401(k) or IRA, into a self-directed IRA that holds physical gold. This strategy allows you to diversify your retirement portfolio and protect your wealth from inflation and market volatility.
Can I roll over my 401(k) into a Gold IRA without penalty?
Yes, you can roll over your 401(k) into a Gold IRA penalty-free by requesting a direct rollover, which transfers funds directly between custodians. If you opt for an indirect rollover, you must complete the transfer within 60 days to avoid IRS taxes and early withdrawal fees.
What IRS rules apply to physical gold in a Gold IRA?
The IRS mandates that physical gold in an IRA must meet a minimum purity standard of 99.5% and be stored in an IRS-approved depository. Additionally, you cannot personally store the gold at your home, as doing so is considered an unauthorized retirement distribution and is subject to heavy penalties.
Are there fees associated with initiating a Gold IRA rollover?
Yes, setting up a Gold IRA involves costs such as one-time account setup fees, annual custodian maintenance fees, and secure depository storage fees. Many top gold IRA providers offer to waive these fees for the first year depending on your initial investment size.